If you import goods into the EU, the Carbon Border Adjustment Mechanism (CBAM) is likely already on your radar. Designed to level the playing field between EU producers and international suppliers, CBAM places a carbon price on certain imported goods based on their embedded emissions. Understanding the financial impact for importers can be complex.
This blog provides a clear overview of CBAM’s financial implications, including its mechanics, CBAM certificate pricing, key timelines, and practical strategies to support CBAM compliance and effective cost management.
CBAM is meant to prevent carbon leakage by ensuring that the price of imports accurately reflects their carbon content. This mechanism aims to equalize the carbon price paid by EU domestic producers, who are subject to the EU Emissions Trading System (ETS), and the carbon price of imported goods.
Materials in Scope
The CBAM regulation currently covers imports of the following carbon-intensive goods:
- Iron and steel
- Aluminum
- Cement
- Fertilizers
- Electricity*
- Hydrogen
* Electricity in this context refers to physical electricity imported into the EU grid from neighboring countries, not a manufacturing input.
CBAM Timeline and Who Must Act
The definitive CBAM regime began on 1 January 2026. Importers or indirect customs representatives importing more than the annual 50-tonne net-mass threshold of CBAM goods must obtain authorised CBAM declarant status or have submitted an authorisation application allowing provisional importation where applicable. CBAM certificates will be sold through the common central platform from 1 February 2027. The first annual CBAM declaration and certificate surrender, covering 2026 imports, is due by 30 September 2027.
Purchasing CBAM Certificates
Authorized CBAM declarants or indirect customs representatives importing more than the 50-tonne annual net-mass threshold must obtain authorised CBAM declarant status and purchase/surrender CBAM certificates. These certificates represent the carbon price that would have been paid if the goods had been produced under the EU ETS.
- How Certificates Are Purchased: From 1 February 2027, Member States will sell certificates to authorised declarants through the common central platform; the declarant’s National Competent Authority is the relevant Member State contact. The number of certificates required will correspond to the reported embedded emissions of their imported goods, adjusted for any carbon price already paid in the country of origin and with a free allocation reduction.
- When Certificates Need to be Purchased: Importers or indirect customs representatives that submitted an authorisation application by 31 March 2026 may continue importing CBAM goods provisionally until the competent authority decides on the application. This transitional application deadline has now passed. Importers that are not authorised—or were not eligible for this provisional arrangement—risk having CBAM goods refused entry into the European Union and may face significant penalties.
- CBAM certificates will be available for purchase from 1 February 2027 and surrendered annually. From 2027, authorised CBAM declarants must also meet quarterly certificate coverage requirements.
- Annual CBAM declarations and certificate surrender must be submitted by September 30, 2027, covering emissions from goods imported in 2026.
- This declaration and surrender of certificates process will continue annually.
- Certificate Coverage: From 2027, authorised CBAM declarants must hold CBAM certificates covering at least 50% of year-to-date embedded emissions on a quarterly basis.
- Repurchase requests must be submitted by 31 October of the year in which certificates were surrendered. Repurchase is limited under Article 23. On 1 November each year, the Commission cancels CBAM certificates purchased during the year before the previous calendar year that remain in the declarant’s account.
CBAM Penalties for Non-Compliance
- Permanent System: For failure to surrender required CBAM certificates by 30 September, the penalty equals the EU ETS excess emissions penalty under Directive 2003/87/EC Article 16(3), increased under Article 16(4), per unsurrendered CBAM certificate. Unauthorised import penalties may be three to five times that penalty.
- Additionally, non-registrants may face potential loss of market access, as the European Commission and the National Competent Authority of each member state will be cross-checking authorized status of imports with the CBAM Registry. Customs authorities are prohibited from allowing importation of CBAM goods by anyone other than an authorised CBAM declarant, unless the de minimis exemption is satisfied.
Overview of the CBAM Certificate Purchasing System
Importers will utilize a dedicated CBAM registry to manage their certificate accounts.
- Account Management: Importers will need to establish an account in the CBAM registry, where they will purchase, hold, and surrender certificates.
- Annual Surrender: By September 30 every year, starting with September 30th, 2027 for 2026 imports, authorized CBAM declarants must surrender the number of CBAM certificates for goods imported in the previous calendar year, after applicable adjustments.
- Benchmark Values and Free Allowances: The system incorporates benchmark values and a phase-out of free allowances for EU producers to ensure a fair transition. This means importers initially do not pay for 100% of their embedded emissions, as a portion is deducted based on a benchmark and phase-in factor, aligning with the gradual phasing out of free allowances for EU producers. This mechanism ensures that importers and EU producers are treated equitably during this transitional period.
CBAM Certificate Pricing
The CBAM financial obligation is determined by the number of CBAM certificates to be surrendered, which corresponds to declared embedded emissions after reductions for an effectively paid third-country carbon price and after the adjustment reflecting EU ETS free allocation. Certificate prices are calculated under Article 21: quarterly average EU ETS auction closing prices for 2026 embedded emissions and weekly average EU ETS auction closing prices thereafter.
(1 ton of CO2e = 1 CBAM certificate)
Calculating Embedded Emissions and CBAM Cost
The following formulas are derived from the methodology for calculating embedded emissions for simple goods under the CBAM Regulation.
The following formulas show the main inputs used to calculate embedded emissions and estimate certificate-related CBAM costs for covered imports.
At a high level, CBAM is designed to create equivalent carbon pricing between imported goods and goods produced in the European Union under the European Union Emissions Trading System (EU ETS). However, the full CBAM cost is not applied immediately. During the phase-in period, the number of CBAM certificates to be surrendered is adjusted to reflect the extent to which comparable EU producers still receive free EU ETS allowances. As those free allowances are gradually reduced, the importer’s CBAM certificate obligation increases over time, meaning the effective carbon cost phases in progressively. This adjustment continues until 2034, when the CBAM factor for free allocation no longer applies and the CBAM obligation reaches full application.
CBAM cost and embedded emissions are calculated for each CBAM good by Combined Nomenclature (CN) code and country of origin, and, where applicable, by the production process associated with that CN code.
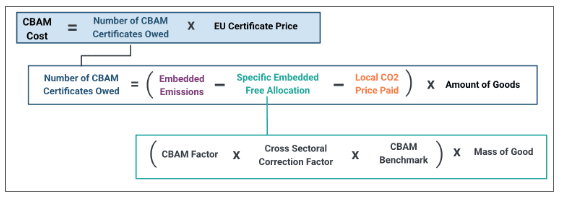
Formula Definitions:
CBAM Certificate Price: The price in euros calculated and published by the European Commission under the CBAM certificate pricing rules. In 2026, the Commission publishes quarterly prices; from 2027 onward, it publishes weekly prices.
Embedded Emissions: tCO2e /ton of emissions embedded in the imported CBAM good, calculated using actual data, default values, or a combination approach as permitted under CBAM methodology.
Local (Third-Country Carbon Price Paid: A carbon price that has been effectively paid in the country of origin for the embedded emissions in the CBAM good, where eligible for a reduction under Article 9 of Regulation (EU) 2023/956.
Amount of Goods: Total volume imported in tons of the CBAM good in the reporting period.
CBAM Factor: The percentage used under the European Union Emissions Trading System (EU ETS) to reflect the remaining free allocation available to comparable EU producers during the CBAM phase-in period. The CBAM reduction factor for 2026 is 97.5%, meaning the financial adjustment or phase-in charge applies to 2.5% of the embedded emissions of imported goods. The factor increases as the free allocation is phased out over time, reaching 100% in 2034.
Cross Sectoral Correction Factor: The CSCF is an EU ETS mechanism to reduce the total free allowance allocations across all goods and sectors. It is applied only if an adjustment is needed in the case of total free allocations exceeding the maximum amount available, and is published by the European Commission. For the 2026–2030 allocation period, the European Commission has set the cross-sectoral correction factor at 100%.
CBAM Benchmark: tCO2e /ton of product. Benchmark values are reference emissions values used to adjust an importer’s CBAM certificate obligation during the phase-in period.
Mass of Good: Mass in tons of one unit of CBAM good.
Default Values vs. Actual Values
CBAM declarants can choose to use either default or actual values when calculating embedded emissions. CBAM default values are designed to be financially punitive and to discourage reliance on estimated emissions data where actual installation-level data can be obtained. As a result, default values may increase reported embedded emissions and therefore increase the number of CBAM certificates an importer must surrender compared with lower verified actual emissions. This financial impact is expected to become more significant over time as the CBAM financial obligation phases in alongside the phase-out of free allowances under the European Union Emissions Trading System, reaching full application by 2034.
Default Values: For goods other than electricity, CBAM default values are set at the average emission intensity of the exporting country for each covered good, increased by a proportionately designed mark-up. The mark-up for 2026 is 10%, 2027 is 20%, and 2028 is 30%. Where reliable exporting-country data cannot be applied, the default value is based on the average emission intensity of the 10 exporting countries with the highest emission intensities for which reliable data can be applied.
- The European Commission has published the definitive-period CBAM default values for 2026 on its CBAM Legislation and Guidance page, alongside Commission Implementing Regulation (EU) 2025/2621, which sets the legally binding default values. The Commission also provides an Excel version for information purposes to help users identify the applicable value.
Actual Values: Actual values are calculated at the installation level and takes into account the direct and in some cases, indirect emissions, associated with the production of the CBAM good. If actual values are used, third-party verification from accredited verifiers will be required. Verification normally includes an installation visit; a visit may be waived only where the applicable criteria are met. More information on verification principles can be found in Commission Implementing Regulation (EU) 2025/2546.
CBAM Certificate Pricing
In 2026, the European Commission will calculate and publish 4 quarterly prices, one for each calendar quarter. From 2027 onwards, the Commission will calculate and publish weekly prices.
- Each quarterly price in 2026 will be calculated by the Commission during the first calendar week following the end of the relevant quarter. The calculation is based on publicly available information related to EU ETS auctions.
- Each quarterly price in 2026 will apply to the sales of CBAM certificates corresponding to emissions in CBAM goods imported into the Union during that quarter. Published pricing can be found here.
How to Strategically Control CBAM Costs in the Long Term
Default values can be simpler to use in the short term because they require less supplier engagement and fewer installation-specific data inputs. However, they are based on generalized assumptions rather than verified production data and, for goods other than electricity, include a proportionately designed mark-up. This can increase reported embedded emissions and, in turn, increase the number of CBAM certificates that must be surrendered where actual emissions would otherwise be lower. Relying on defaults also limits visibility into the specific production processes, and supplier-level emissions drivers that determine CBAM exposure.
Actual values require more work upfront, including supplier engagement, data collection, and verification, but they can create a stronger long-term cost-control strategy. Installation-level emissions data gives CBAM declarants better visibility into what is driving their certificate obligation and where cost-reduction opportunities may exist. It also allows companies to compare suppliers, production routes, and product processes more accurately, which can support sourcing decisions that reduce CBAM exposure over time.
The earlier companies begin collecting actual values and building supplier readiness, the sooner they can reduce dependence on default values, improve forecast accuracy, and shift CBAM from an ever-increasing cost and risk into a more strategic sourcing and cost-management program.
CBAM Regulatory Expertise & Supplier Support
- Regulatory Expertise: Assent’s team of regulatory experts monitor the latest updates with CBAM legislation and implementation. This team is available as a resource to provide support and education, and address any questions around CBAM compliance.
- Supplier Focused Support: Assent’s Supplier Support team operates across time zones and provides support in multiple languages. They can answer any and all questions suppliers may have. Suppliers have access to Assent’s Supplier Help Center to get guidance and education on providing accurate data.
Assent CBAM software helps importers navigate CBAM requirements with confidence, from emissions data collection to calculating embedded emissions. Book a demo to see how Assent can support your CBAM strategy.
FAQ: CBAM Certificates & Financial Impact
Get answers to the most common questions about the financial impact of the EU Carbon Border Adjustment Mechanism (CBAM).
This information is provided for educational purposes only and does not constitute legal or regulatory advice. The information is current as of the date of publication or send. Your organization remains responsible for confirming compliance obligations.